Non-Fault Accident: What to Do Step by Step (UK 2026)
Someone Hit Your Car and It Wasn't Your Fault. Here's Exactly What to Do
A non-fault accident puts you in a strange position: you did nothing wrong, yet you're the one dealing with the damage, the phone calls and the disruption. The good news most drivers don't know is that being the non-fault party comes with real entitlements, and the decisions you make in the first hour and the first day decide whether you actually receive them.
At the scene
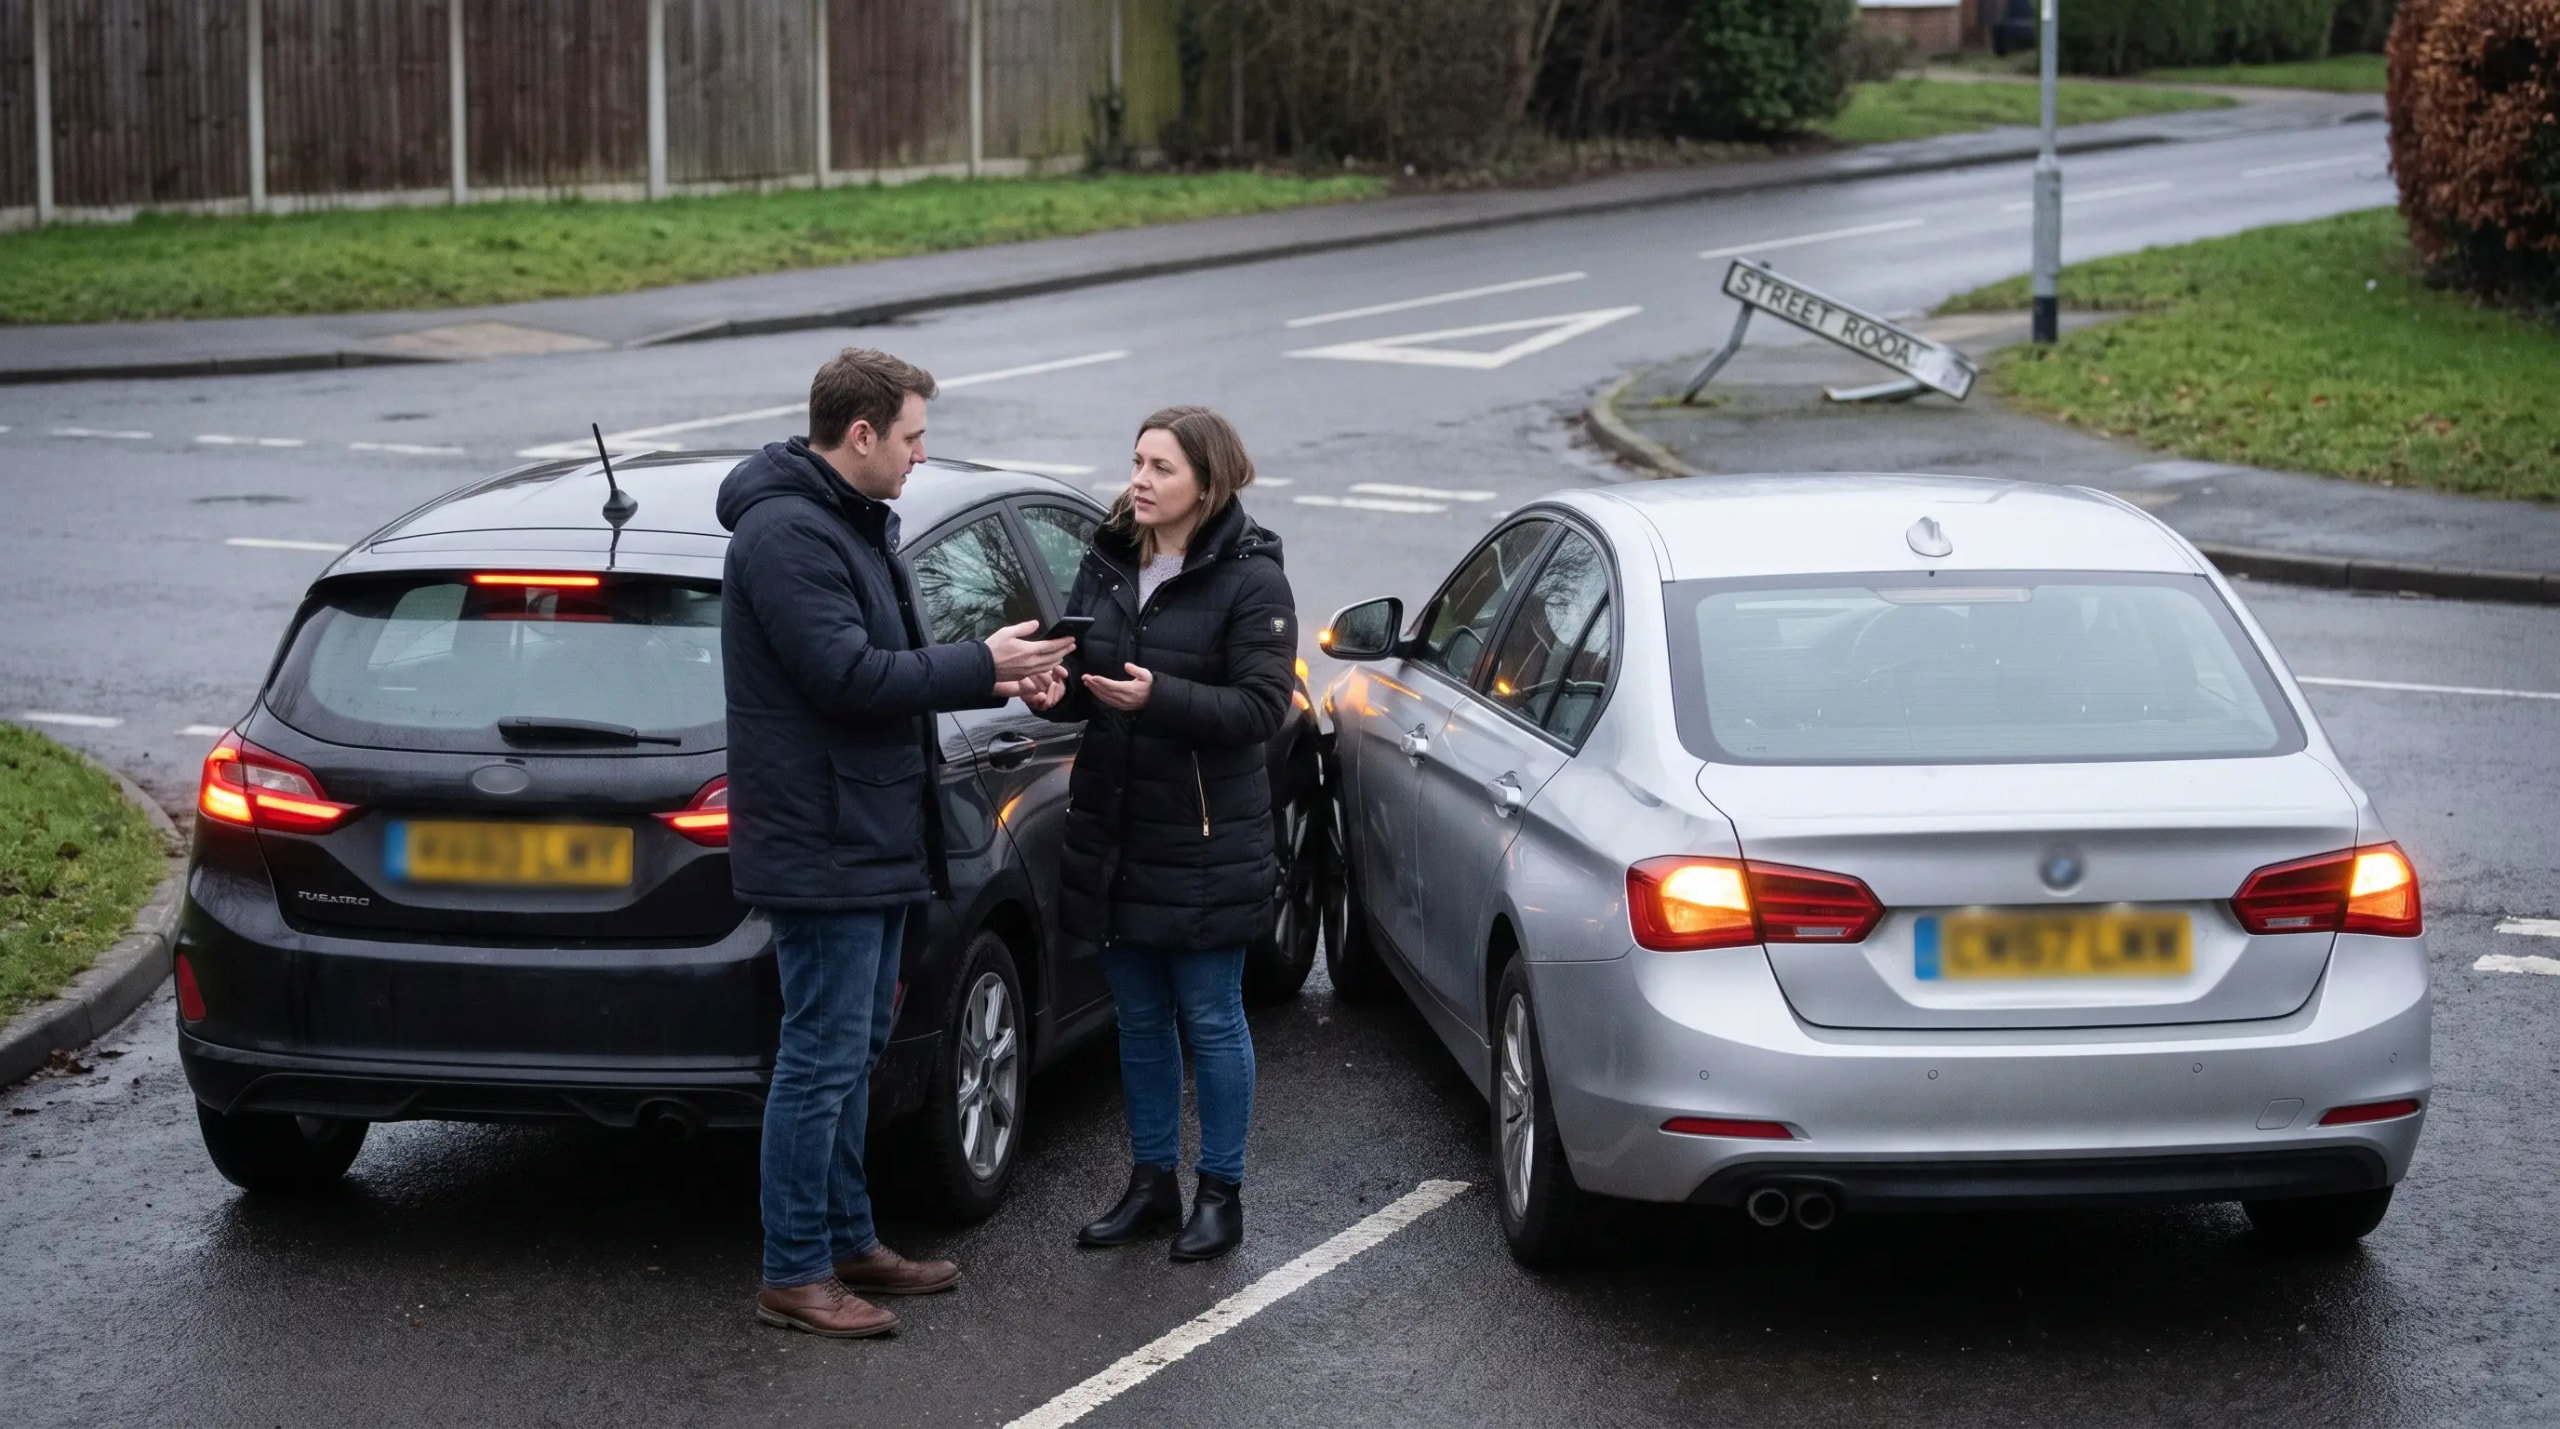
Stop, make the scene safe, and check everyone is okay. Then gather what protects you later: the other driver's name, contact details, registration and insurer, plus photos of both cars, the damage, the positions and the road. Independent witnesses are gold; take a number if anyone stopped. Note the time, location and what happened while it's fresh. If the other driver won't stop or has no insurance, report to the police promptly.
Say nothing that sounds like accepting blame, even politely. Liability gets decided on evidence, not on doorstep apologies.
The decision that separates informed drivers from everyone else
Your instinct will be to ring your own insurer and claim. You can, but for a genuine non-fault accident there's a second route: because the at-fault driver's insurer is liable for your losses, a claim can be run against their policy instead of yours. Where the non-fault criteria are met, you don't need to make a claim against your own policy at all, which is the difference between paying your excess and hoping to recover it later, or never touching it in the first place.
This is exactly what accident management exists for, and it's why we launched Second Gears Accident Care: one call, and the claim is handled against the at-fault insurer, with a dedicated handler managing the whole process, liaising with insurers, witnesses and the repairer, and a replacement vehicle sorted while yours is off the road.
Your entitlements as the non-fault party
Where liability is clear, you're typically entitled to have your vehicle repaired properly at no cost to you, a like-for-like replacement vehicle rather than whatever courtesy car is spare, recovery and storage if the car can't be driven, and your out-of-pocket losses recovered from the at-fault insurer. Our replacement vehicle guide covers the like-for-like point in detail, because it surprises almost everyone.
Which insurer should handle it?
The route you claim through decides your excess, your no-claims position and who does the chasing. We've broken the decision down properly in claim on my insurance or theirs? and how a non-fault accident affects your insurance and NCB.
If the car turns out to be a write-off
A non-fault write-off has its own playbook, including the retention decision that can put thousands back in your pocket. Read our non-fault write-off guide before accepting any settlement figure.
Get it handled properly
Report your non-fault accident through Second Gears Accident Care and a specialist team manages the claim against the at-fault driver's insurer: repairs, replacement vehicle, recovery, the lot, at no cost to you as the non-fault driver.
Someone Hit Your Car and It Wasn't Your Fault. Here's Exactly What to Do
A non-fault accident puts you in a strange position: you did nothing wrong, yet you're the one dealing with the damage, the phone calls and the disruption. The good news most drivers don't know is that being the non-fault party comes with real entitlements, and the decisions you make in the first hour and the first day decide whether you actually receive them.
At the scene
Stop, make the scene safe, and check everyone is okay. Then gather what protects you later: the other driver's name, contact details, registration and insurer, plus photos of both cars, the damage, the positions and the road. Independent witnesses are gold; take a number if anyone stopped. Note the time, location and what happened while it's fresh. If the other driver won't stop or has no insurance, report to the police promptly.
Say nothing that sounds like accepting blame, even politely. Liability gets decided on evidence, not on doorstep apologies.
The decision that separates informed drivers from everyone else
Your instinct will be to ring your own insurer and claim. You can, but for a genuine non-fault accident there's a second route: because the at-fault driver's insurer is liable for your losses, a claim can be run against their policy instead of yours. Where the non-fault criteria are met, you don't need to make a claim against your own policy at all, which is the difference between paying your excess and hoping to recover it later, or never touching it in the first place.
This is exactly what accident management exists for, and it's why we launched Second Gears Accident Care: one call, and the claim is handled against the at-fault insurer, with a dedicated handler managing the whole process, liaising with insurers, witnesses and the repairer, and a replacement vehicle sorted while yours is off the road.
Your entitlements as the non-fault party
Where liability is clear, you're typically entitled to have your vehicle repaired properly at no cost to you, a like-for-like replacement vehicle rather than whatever courtesy car is spare, recovery and storage if the car can't be driven, and your out-of-pocket losses recovered from the at-fault insurer. Our replacement vehicle guide covers the like-for-like point in detail, because it surprises almost everyone.
Which insurer should handle it?
The route you claim through decides your excess, your no-claims position and who does the chasing. We've broken the decision down properly in claim on my insurance or theirs? and how a non-fault accident affects your insurance and NCB.
If the car turns out to be a write-off
A non-fault write-off has its own playbook, including the retention decision that can put thousands back in your pocket. Read our non-fault write-off guide before accepting any settlement figure.
Get it handled properly
Report your non-fault accident through Second Gears Accident Care and a specialist team manages the claim against the at-fault driver's insurer: repairs, replacement vehicle, recovery, the lot, at no cost to you as the non-fault driver.
Related Articles
Does a Non-Fault Accident Affect Insurance and NCB?
Does a Non-Fault Accident Affect Your Insurance? The Answer Nobody Likes, and the FixHere's the truth the renewal letter delivers eventually: yes, a n...
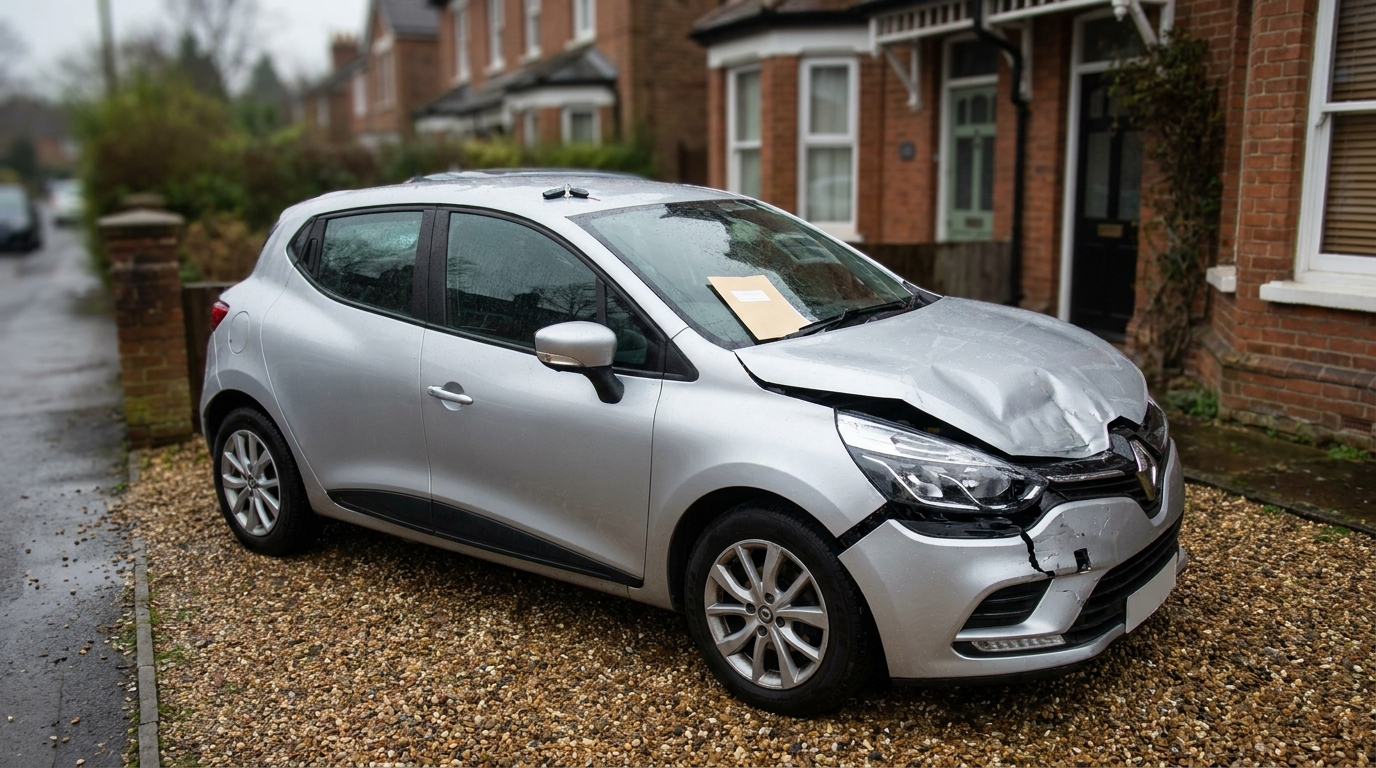
How Much Is My Written-Off Car Worth? The Honest Answer for UK Sellers in 2026
How Much Is My Written-Off Car Worth? The Honest Answer for UK Sellers in 2026If your car has just been written off, the first question is almost alwa...
How to Sell a Car With Outstanding Finance in the UK
If you want to sell your car but still have a finance agreement running on it, you are not stuck. But you do need to handle it correctly.Selling a car...